Vertical integration in watchmaking means making the watch’s parts in-house instead of buying them: the movement components, the case, the dial, the hands, the bracelet. The industry’s prestige word for a deeply integrated company is “manufacture,” and brands spend real money earning the right to use it. The useful question is not whether a brand says “in-house” but what exactly is made in whose house, because even the most integrated watch companies buy some components, and the word has no legal definition.
What the words mean
A manufacture, in the traditional sense, is a company that designs and produces its own movements rather than buying finished or semi-finished movements from a supplier. “In-house” usually means the same thing but is looser: it can describe a movement, a case, or a dial depending on the sentence. The historical contrast is the établisseur, the assembler who bought movements, cases, dials, and hands from specialists and put them together under one brand name. For most of watchmaking history, the établisseur model was the norm and nobody was embarrassed by it; the component trades (case makers, dial makers, hands makers, spring makers) were industries in their own right.
There is no certification body for “manufacture” and no legal threshold. It is a description a brand applies to itself, which means it is marketing language first and a technical claim second. Collector consensus treats the term as meaningful anyway, but only when you can point to what is actually made on site.
What “in-house” usually covers, and what it does not
When a manufacture says its movement is in-house, it generally means the design, the mainplates and bridges, and the going train are produced under its control. Cases are the next frontier: historically almost everyone bought cases from specialist case makers, and brands that machine their own cases today (Rolex is the famous example) are the exception proving the rule. Dials are similar; even large houses have long bought dials from specialists.
Then there is the list of things almost nobody makes. Hairsprings are the classic example: the tiny spiral that regulates the whole watch is brutally difficult to produce consistently, and for decades the industry’s supply ran through a handful of specialists (today mostly within the Swatch Group). Only a few companies make their own, and many respected manufactures buy them without apology. Jewels, hands, crowns, crystals, and straps are routinely bought in, and straps in particular expose the absurdity of demanding 100 percent: nobody expects a watch company to tan its own leather. When a brand says “made completely in-house,” it is describing the movement, not the cow.

The part no supply chain can replace: assembly, adjustment, and finishing still happen at the bench, in-house or not. Photo: Wikimedia Commons, CC BY-SA 3.0 (Serbia).
Who is actually integrated
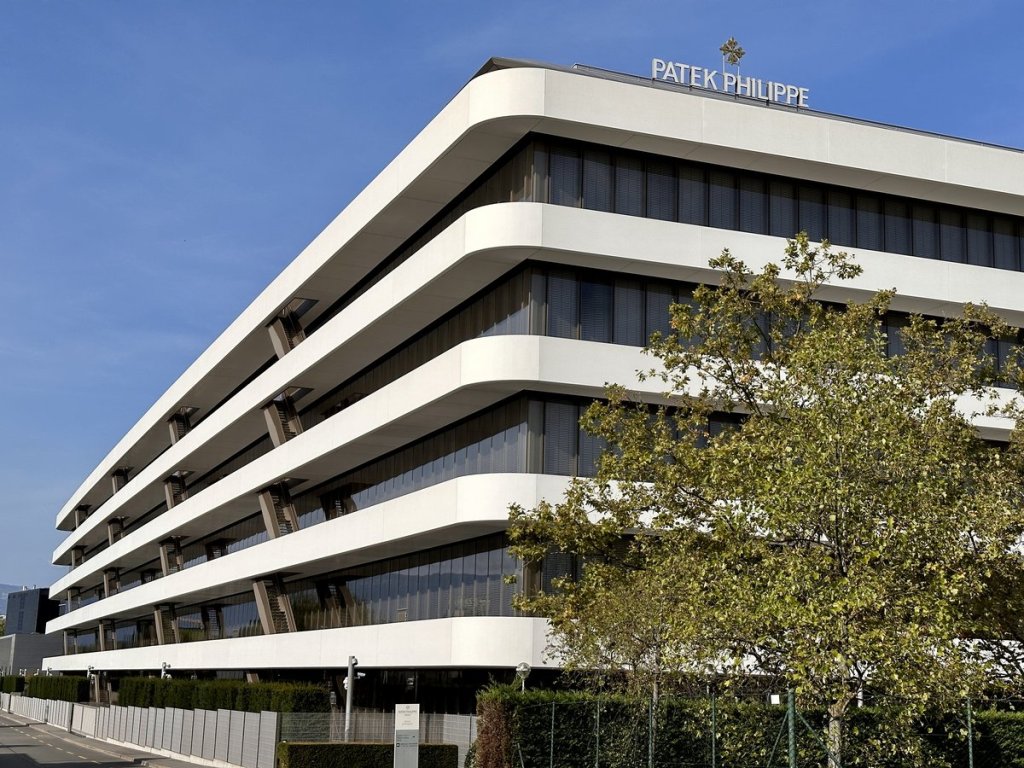
A short list of companies whose integration is well documented, with the usual warning that “well documented” and “total” are different things. Rolex makes its own movements, cases, bracelets, and dials, and operates its own gold foundry; this is among the deepest integration in the Swiss industry (widely reported, consistent across sources). Patek Philippe, Audemars Piguet, and Vacheron Constantin design and produce their movements in-house, with varying degrees of case and dial production. Jaeger-LeCoultre has manufactured movements for much of the industry for over a century, which is integration of a different kind: it was the supplier before it was the brand. A. Lange and Söhne builds its movements in Glashütte with a famously high share of in-house components.
Outside Switzerland, Seiko’s integration runs unusually deep for its prices: the company produces movements, cases, dials, crystals, and lubricants across its group companies (widely reported; the exact component list varies by source, so treat sweeping claims with care). The Swatch Group is integrated at the group level rather than the brand level: ETA makes movements, Nivarox makes hairsprings and escapements, and the components flow between sister brands, which is vertical integration owned by the group, not the name on the dial. Bovet reports producing more than 95 percent of its components in its own facilities, including hairsprings and increasingly cases (brand claim via trade press, October 2026).
A footnote to every name on this list: each of them buys something. Hairsprings, jewels, hands, and straps flow between even the proudest manufactures. “In-house” has always meant “the important parts,” and the definition of important is the brand’s to choose.
The middle ground, where most watches live
Below the manufactures sits the industry’s broad middle, and it deserves a fair hearing rather than a sneer. Many good brands design their own movements but buy components; many buy complete ébauches (movement blanks) from suppliers like Sellita and finish, decorate, and regulate them in-house. After Switzerland’s competition authority wound down ETA’s third-party supply between 2013 and 2020, Sellita became the dominant independent supplier, reportedly producing around a million mechanical movements a year, and Tudor began selling its own Kenissi calibers to outside brands like Norqain (trade press reporting and analysis). None of this is shameful. It is the modern version of the établisseur model, and the quality of the finished watch depends on what the brand does with the parts, not whose logo is on the purchase order.

The American Waltham Watch Company pioneered the vertically integrated watch factory in the 19th century, making nearly everything under one roof with interchangeable parts. Integration is older than the marketing word for it. Photo: Wikimedia Commons, CC BY-SA 3.0.
Why it matters, and where it is marketing
The business case for integration is real. Controlling the supply chain means a brand cannot be cut off by a supplier, can design movements no competitor can buy, and can guarantee parts availability for servicing decades later. That last point is the one collectors feel most directly: an in-house caliber serviced by its maker is a watch that stays repairable, while an orphaned outsourced caliber can become a paperweight if the supplier disappears.
The marketing case is where the dry eye comes in. “In-house” is used as a quality signal, but ownership is not the same as execution. A Sellita-based watch from a careful brand, well finished and honestly regulated, can be a better watch than a sloppy in-house caliber with pretty press photos. Integration tells you about the company’s structure and its supply risk. It tells you nothing about whether the watch on your wrist is well made. Judge the watch, not the org chart.
Keep digging
Integration decides who makes the parts; Quality Control decides whether those parts are good enough, and Testing proves what the finished watch can do. For the movements at the center of the whole question, see Movements, and for the brands most associated with the manufacture model, see Brands.
Why it matters
Vertical integration shapes the industry’s economics, its supply chains, and its marketing language all at once. Understanding it means you can separate the structural advantages (supply security, serviceability, design freedom) from the sales pitch, and give full credit to the well-made outsourced watch that the “in-house or nothing” crowd would have you dismiss.
Thanks for reading this.

